# Ten-year liability insurance for renovations in Belgium: what is covered?
Ten-year liability insurance does not cover every defect. Before renovating, check whether the project falls under the compulsory scheme, which damage is insured and which certificate relates to the work. The [Belgian Federal Public Service Economy explains the Belgian scheme](https://economie.fgov.be/fr/themes/services-financiers/assurances/construction/assurance-responsabilite). A certificate guarantees neither the absence of defects nor automatic compensation.
## Does your renovation fall under the obligation?
The conditions must be considered together:
- The work concerns a home in Belgium.
- An architect's involvement is legally required.
- Final planning permission was issued after 1 July 2018, subject to transitional rules.
- The services may give rise to the professional's ten-year liability.
Voluntarily consulting an architect is not enough. For an older project, have the dates and transitional arrangements for agreements governed by the Breyne Law checked. [Articles 2, 5, 21 and 22 of the Law of 31 May 2017](https://www.ejustice.just.fgov.be/eli/loi/2017/05/31/2017030353/justel) govern these conditions.
## Which damage is actually covered?
The compulsory scope concerns the home's structural strength and stability. The watertightness of the enclosed structural shell is concerned when it threatens that strength or stability. Water ingress alone therefore does not prove cover.
The law excludes, among other things, aesthetic damage, pure non-material damage (dommages immatériels purs) and damage that was apparent or known to the insured at provisional acceptance, or resulted directly from defects they knew about then. [Articles 3 and 7 clarify this scope](https://www.ejustice.just.fgov.be/eli/loi/2017/05/31/2017030353/justel).
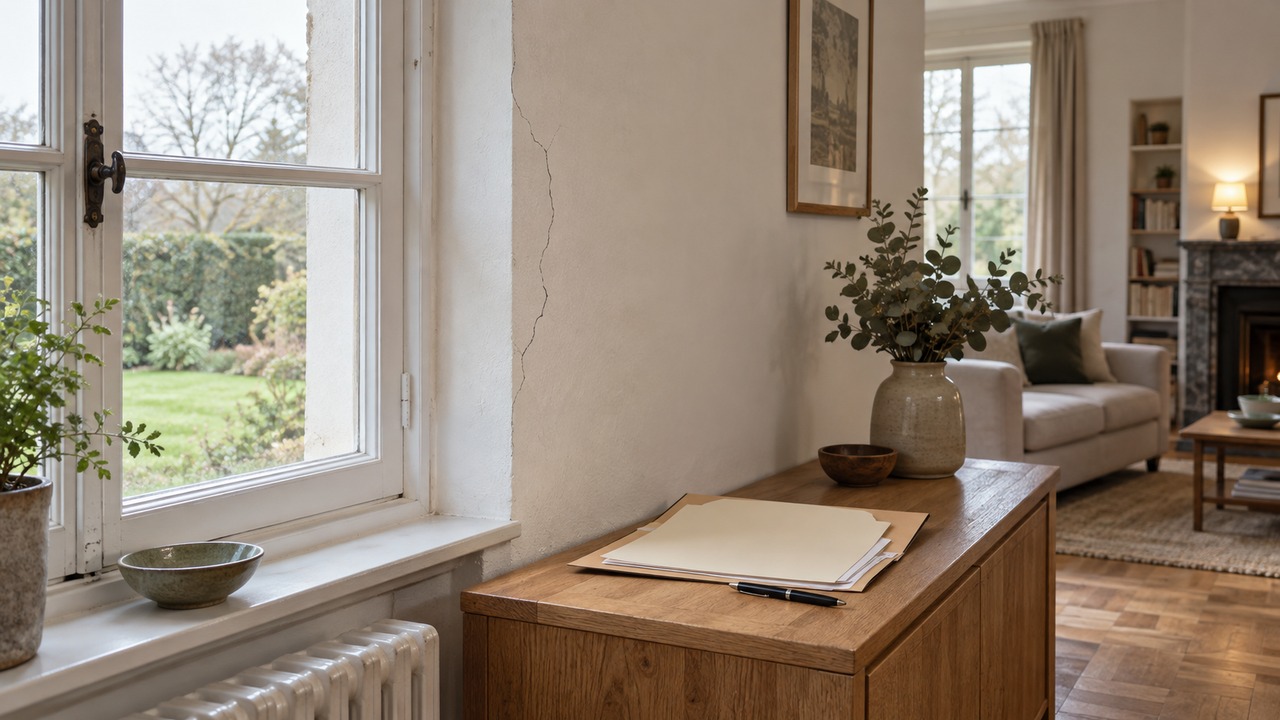
A crack calls for a diagnosis, not a conclusion from a photograph. Ask about the examination's cost before commissioning it. An insurance exclusion does not necessarily remove all liability: potential remedies must be considered separately.
## How should you check the amounts and duration?
The minimum level of cover and exclusion threshold are indexed. Ask the insurer to distinguish the statutory minimum, policy limit and excess, then quote for additional cover. [Articles 3 and 6 set the bases and ABEX indexation](https://www.ejustice.just.fgov.be/eli/loi/2017/05/31/2017030353/justel).
The ten-year period starts with formal acceptance of the works, known in Belgium as 'agréation'. The final invoice or provisional acceptance does not automatically establish that date: keep the contracts and records.
Articles 38 and 39 of the [Law of 22 July 2026](https://www.ejustice.just.fgov.be/eli/loi/2026/07/22/2026005775/justel) amend articles 3 and 7 of the Law of 2017. Article 50 sets the general entry into force at 1 September 2027; article 49 governs the transition for Book 7 of the Civil Code. For a file spanning that date, have the applicable rules checked rather than assuming all policies automatically switch over.
## Which documents should you request before work and keep for a sale?
Contractors and other service providers subject to the scheme give their certificate to the client commissioning the work and the architect before work begins. Contractual documents state the insurer, its enterprise number and the policy number. In particular, check:
- the insured professional and their activity;
- the address, works and planning permission references;
- the cover, exclusions and parties actually insured.
A policy may be annual or project-specific. A combined policy may exempt covered parties from holding an individual policy for that project. [Articles 8, 12 and 19/2 govern these documents](https://www.ejustice.just.fgov.be/eli/loi/2017/05/31/2017030353/justel).
Insurance follows the property for the remaining period: a sale does not restart the ten years. For a transfer of rights in rem during that period, article 12 provides for the notary to consult the register and record the result in the deed. Gather certificates, contracts and evidence of acceptance with the other [documents for selling a house in Belgium](https://youhome.immo/en/journal/documents-selling-house-belgium/).
## What are the answers to frequently asked questions?
### Is a mention on the quotation enough?
No. Request the certificate and have its correspondence with the professional, project and works checked.
### Does ten-year liability insurance replace works insurance?
No. Defects giving rise to liability and damage during building work address different needs. Have cover, excesses and premiums compared with your insurer.
### What should you do if a defect appears?
Keep dated photographs and documents. Contact the professionals concerned promptly, then the insurer or intermediary. Have the deadlines and cost of any expert assessment checked.
In the Province of Liège, our method distinguishes presenting the property from checking insurance cover. To prepare your sale project, you can [request your valuation report](https://youhome.immo/en/valuation/request/).
Practical guides
Ten-year liability insurance for renovations in Belgium: what is covered?
Relevant works, insured damage and certificates: useful checks before renovating and later selling in Belgium.